Luno Says Stablecoins Alone Cannot Fix Africa’s Cross-Border Payment Challenges
Ayotunde Alabi says that stablecoins can improve settlement, but they cannot independently solve Africa's fragmented financial systems.


Table Of Content
What to Know:
- Ayotunde Alabi, Luno Nigeria CEO, has called for improved financial connectivity across Africa.
- Alabi says that stablecoins can improve settlement, but they cannot independently solve Africa’s fragmented financial systems.
- Cross-border payments across the continent costs between 7.4 to 8.4%, driven by intermediary hops and FX spreads.
- Luno has spent 2026 expanding its institutional services via the launch of the ZARU stablecoin, acquisition of GTXN and securing foreign licences.
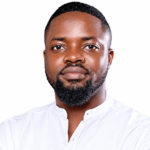
Speaking in Lagos, at a stakeholder convergence on the future of digital financial infrastructure, Luno Nigeria CEO Ayotunde Alabi delivered a pointed reality check to the African digital asset industry.
Alabi said, “Stablecoins present a significant opportunity to make cross-border payments faster, cheaper, and more efficient, but they are not, on their own, the solution to Africa’s fragmented financial systems.”
While stablecoins have been used to improve the speed and reduce the cost of cross-border payments on the continent, Alabi says what Africa needs is better financial connectivity, regulatory alignment, and currency interoperability.
Why Cross-Border Payments Remain Expensive in Africa
Africa remains the most expensive continent to send money to and within. At least 40 distinct national currencies circulate across the continent, making direct currency pairs rare and liquidity shallow.
The African Development Bank’s African Economic Outlook 2026 estimates cross-border payments in Africa carry an average cost of 7.4% to 8.4%. Correspondent banking is a major driver of that expense. SWIFT reports that 48% of African Payments settle outside the continent. The United States alone accounts for 39% of the continent’s financial flows.
Each hop in this system means added FX spreads of up to 3-8%, banking fees, compliance checks and costs, and multi-day clearing delays. For an African business transferring $100,000 across borders, an 8% friction cost translates into $8,000 lost to fees and spreads. The multi-day settlement also means businesses’ capital is not as readily available.
The cost is not negligible. Cheaper cross-border payments could strengthen African trade, leading to up to $292 billion in income gains.
Why Stablecoins Alone Cannot Solve the Problem
Stablecoins can reduce some of this friction. Transactions that take days to settle are settled often within minutes, and the lack of multiple intermediaries often translates to reduced cost.
An X user recently experimented with this effect. Using 10 different payment rails, he sent $1,000 from New York to Lagos.
According to him, the P2P USDT route delivered ₦1,457,800 to Lagos within minutes. SWIFT charged him $40 and delivered ₦1,300,600 within three to five business days.
The impact of stablecoins and digital asset rails on cross-border payments is well documented, which is why they’re increasingly being used as settlement infrastructure by fintechs across the continent.
However, a digital dollar moving rapidly between two crypto wallets does not automatically pay a local supplier’s invoice, clear customs duties, or fund local payroll. The recipient still needs to convert the funds into local currency and cash them out. This is the off-ramp problem.
For stablecoin payments in Africa to work at commercial scale, the “last mile” or “off-ramp” requires deep local currency liquidity, compliant banking off-ramps, and regulated payout rails. Without local payout infrastructure, liquidity and compatible regulation, faster transfers do not automatically mean cheaper or easier payments.
Luno Expands its Institutional Financial Infrastructure
Alabi’s remarks also reflect a shift in Luno’s business model. After building its reputation and business on retail trading, Luno has recently begun focusing on the institutional arm of its business.
Over the past year, Luno has assembled a multi-layered institutional stack meant to serve banks, fintechs, and cross-border enterprises, including:
- API infrastructure enabling banks, fintechs, and asset managers to embed digital asset custody and trading directly into existing financial apps.
- Stablecoin Infrastructure with BlockTower. The company is part of a consortium which launched the South African rand-backed stablecoin, ZARU.
- Obtaining a Class F Digital Asset Business (DAB) license from the Bermuda Monetary Authority (BMA), which enables it to deliver OTC trading, Crypto-as-a-Service, and Global settlement infrastructure to its institutional and B2B clients.
- Acquisition of GTXN to develop a dedicated layer connecting emerging and developed market corridors.
A Different Route to the Same Problem
Luno is not alone in tackling this problem. In November 2026, Stripe-owned payments giant Paystack unveiled its Global Stack API. The Global Stack AP connects its network of over 400,000 African businesses and 50+ partner banks directly to on-chain settlement on the Solana blockchain.
Luno’s GTXN, on the other hand, is a cross-border payments network with licensed collection and payout infrastructure. This regulatory reach and infrastructure are meant to provide the local legs that stablecoins lack on their own.
They start from different positions: Paystack from payment acceptance, Luno from crypto liquidity, and licensed payouts, but they both validate Alabi’s point. Sustainable African financial connectivity requires stitching fiat banking networks and blockchain settlement together.
What Stronger Financial Connectivity Could Mean for African Businesses
If private settlement networks and regional initiatives such as the Pan-African Payment and Settlement System (PAPSS) become more interoperable, the economic impact on intra-African trade would be substantial. Businesses could free up working capital and spend less on payment costs.
However, no single company can bring this vision to life. Regulators and financial institutions need compatible standards, settlement arrangements and compliance frameworks.
Stablecoins are already part of Africa’s financial infrastructure. How widely their benefits spread will depend on integration with banks, liquidity providers, local payment systems and regulators, and not on the technology alone.